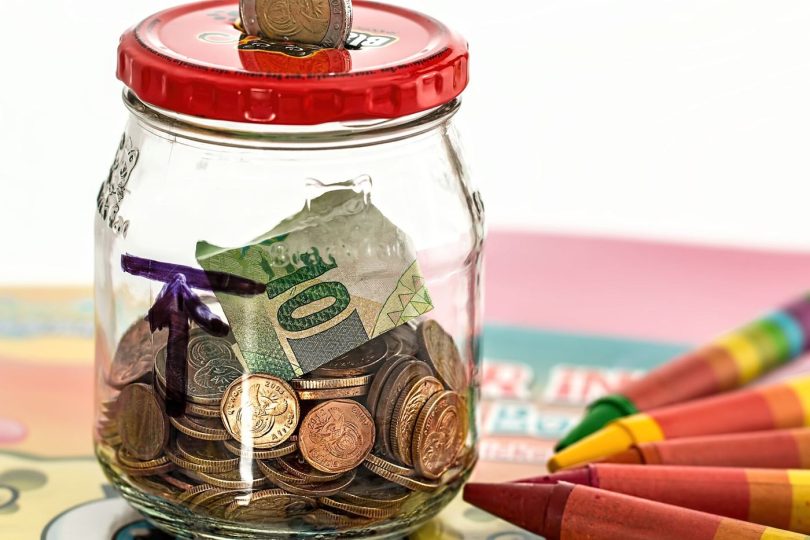

Households are increasingly splitting their savings into separate pots for different purposes, finding that labelled accounts make everyday budgeting calmer and clearer. A common arrangement keeps three pots: one for regular bills that arrive unevenly through the year, one for genuine emergencies such as repairs or a sudden drop in income, and one for planned pleasures like holidays. Moving a small amount into each pot on payday, before spending begins, removes the need for constant willpower later in the month. People who use the system say its main benefit is honesty: a single combined balance can look healthy while quietly including money that is already spoken for, whereas separate pots show at a glance what is truly available to spend without creating a problem next month. For newcomers especially, patient explanation and honest discussion of limits are proving just as valuable as any new feature. The wider point is simple: systems earn confidence when ordinary users can understand them, question them, and use them safely.
What the Evidence Shows
Financial advisers who support the approach suggest starting smaller than enthusiasm suggests, because a routine that survives a difficult month is worth more than an ambitious one abandoned by spring. They also recommend reviewing pot sizes whenever circumstances change, after a pay rise, a new rent, or a child starting school, for example. Keeping the emergency pot in an account that is accessible but not linked to everyday spending cards adds a helpful pause before dipping into it for non-emergencies. None of this requires special products; most banks now allow multiple savings spaces within one account. The enduring lesson is behavioural rather than technical: money that has a named job is less likely to drift away unnoticed, and households feel more in control as a result. As adoption widens, maintaining that plain, careful approach may prove to be the most important discipline of all for everyone involved. Reporting and analysis from sources such as World Bank track the same developments, and specialists following separate savings pots for bills and emergencies say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, separate savings pots for bills and emergencies matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for separate savings pots for bills and emergencies hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.