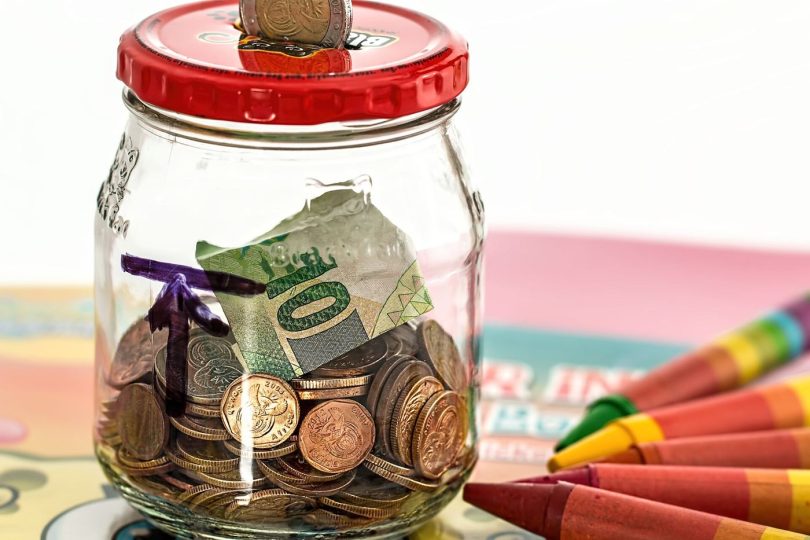

Households are building emergency funds through small, regular contributions, turning a daunting savings goal into a manageable habit. Financial advisers recommend keeping three to six months of essential spending in an easily accessible account, enough to cover a broken boiler, a car repair or a sudden loss of income without resorting to expensive borrowing. For many families, that target once seemed out of reach, but a growing number are reaching it by automating a modest transfer on payday, starting with as little as a few pounds or dollars a week. The approach works because it removes the decision: the money leaves the account before it can be spent, and the balance grows quietly in the background. Surveys suggest that households with even a small emergency cushion report less stress and are far less likely to fall behind on bills when something goes wrong. The habit matters more than the amount, and advisers say starting small beats waiting for the perfect moment.
What the Evidence Shows
Building the fund is only the first step, and advisers say the rules for using it matter just as much. The money should be kept separate from everyday spending, ideally in a different account, so it is not dipped into for holidays or treats. When an emergency does arrive, the fund should be used without guilt, since that is exactly what it is for, and then rebuilt gradually once the crisis has passed. Others split it between an instant-access account for urgent needs and a slightly higher-paying account for larger reserves. Employers and banks are also helping, with some workplaces offering payroll savings schemes that divert a small sum automatically. Consumer groups note that low-income households face the hardest challenge, since finding any spare money is difficult. For most families, the emergency fund is the foundation of financial security, and the peace of mind it brings is worth more than the interest it earns. Reporting and analysis from sources such as World Bank track the same developments, and specialists following emergency fund savings say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, emergency fund savings matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for emergency fund savings hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.