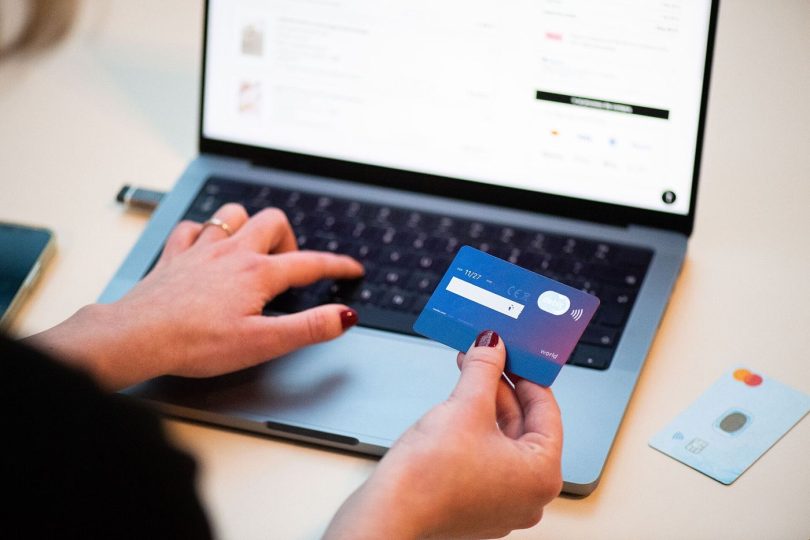

Buy now, pay later has grown from a checkout novelty into regulated consumer credit, and the rules arrived almost everywhere at once. The product lets a shopper take goods immediately and repay in instalments, usually interest-free over a few weeks. In Britain, the Financial Conduct Authority began regulating deferred payment credit on July 15, 2026, requiring providers to be authorised, run affordability checks before every transaction, give customers access to the Financial Ombudsman Service, and offer Section 75 protection on purchases over 100 pounds. The European Union’s revised Consumer Credit Directive applies from November 20, 2026, bringing most buy now, pay later services under consumer credit law for the first time. Australia has regulated the product as credit since June 2025. The United States moved the other way: the Consumer Financial Protection Bureau withdrew its 2024 rule treating these lenders like credit card issuers in May 2025. In August 2025, FICO announced it would include buy now, pay later data in some credit scores.
What the Evidence Shows
The appeal is obvious. Splitting a purchase into four payments feels painless, and for disciplined shoppers it is a free way to spread a cost. The danger is that the painlessness is the point. It is easy to stack several plans at once, lose track of due dates, and miss a payment, which can mean late fees and a mark on a credit file now that the data is being shared with scoring firms. Industry estimates suggest that up to 30 percent of current British users could be rejected under the new affordability checks, including many who have never missed a payment. The safest way to use these plans is to treat them as debt, not as a discount: run one plan at a time, keep a note of every due date, and never use a new plan to pay for an old one. If the instalments would be hard to meet, the purchase is probably too expensive, and waiting is cheaper than borrowing. Reporting and analysis from sources such as World Bank track the same developments, and specialists following buy now pay later regulation say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, buy now pay later regulation matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for buy now pay later regulation hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.